
Home/Insights/Insights
Chapter 13 Versus Foreclosure: Can You Save Your Home?
Facing a missed mortgage payment? Learn how Chapter 13 versus foreclosure works in Illinois, what the automatic stay does, and when to seek legal help.
Insights · 7 October 2026
A foreclosure notice can make it feel as though you have already lost your home. That is not always true. When weighing Chapter 13 versus foreclosure, timing, income, and the amount needed to catch up can change what options remain available. For Illinois homeowners, a Chapter 13 bankruptcy may provide time and court protection to address past-due mortgage payments while keeping the home.
The right path depends on more than whether you are behind. It depends on whether you can afford the mortgage going forward, whether foreclosure has already been filed, what other debts are straining your household, and whether a realistic repayment plan can work.
Chapter 13 versus foreclosure: the basic difference
Foreclosure is the legal process a mortgage lender uses to take and sell a home after missed payments. Illinois uses a judicial foreclosure process, meaning the lender generally must file a lawsuit and obtain court approval before completing a foreclosure sale. That process can take time, but deadlines still matter. Waiting for the final stages can limit your choices and increase costs.
Chapter 13 is a form of bankruptcy designed for people with regular income who need time to reorganize debt. Rather than surrendering the home immediately, a homeowner may propose a repayment plan lasting three to five years. In many cases, the plan allows the borrower to pay mortgage arrears over time while continuing to make the regular monthly mortgage payment.
Chapter 13 does not erase the mortgage or make a home free. It is a structured way to address the amount you fell behind on, provided your budget can support the plan.
What happens when a Chapter 13 case is filed?
Filing a Chapter 13 case generally creates an automatic stay. This is a court order that stops most collection activity right away, including a pending foreclosure lawsuit or sale. For a family facing an imminent sale date, this protection can be significant.
The stay is not a permanent solution by itself. The homeowner must meet Chapter 13 requirements, file required documents, and propose a feasible plan. The mortgage lender may also ask the bankruptcy court for permission to continue foreclosure if the borrower does not make required payments or cannot show a workable path forward.
The protection can be more limited for people who have had recent bankruptcy cases dismissed. A lawyer can review that history before filing so there are no unpleasant surprises at a critical moment.
Catching up on mortgage arrears
A major benefit of Chapter 13 is the ability to spread past-due mortgage payments over the life of the plan. For example, if a homeowner is $18,000 behind and has 60 months to repay the arrears, the plan may require about $300 per month toward that amount, plus any required trustee fees and other debts addressed in the case. The regular mortgage payment must usually continue as it comes due.
That last point is essential. A Chapter 13 plan works only if the household can cover current housing costs and the added plan payment. If the mortgage payment is already unaffordable, filing may delay foreclosure without solving the underlying problem.
Chapter 13 may also help organize other financial pressures, such as credit card balances, medical bills, vehicle debt, or certain tax obligations. Reducing or restructuring those obligations can make it more realistic to keep up with a mortgage. The specific treatment of each debt depends on the facts of the case.
When foreclosure may be the more realistic outcome
No homeowner wants to hear that keeping the property may not be practical. But an honest assessment can protect a family from spending money on a plan that is unlikely to succeed.
Foreclosure or a voluntary transition may be worth considering if the home has become unaffordable because of a long-term income loss, a major change in household expenses, or a mortgage payment that leaves no room for necessities. A Chapter 13 plan cannot fix a budget that remains short every month.
In some cases, selling the property before foreclosure is completed may preserve equity and give the owner more control over the timing of a move. In others, negotiating a loan modification, repayment agreement, short sale, or deed in lieu of foreclosure may be possible. Each choice has different financial and legal consequences, including potential tax issues and effects on other liens.
A foreclosure judgment can also create concerns beyond the loss of the home. Depending on the circumstances, borrowers may face questions about deficiency liability, fees, and the effect on credit. Do not assume the lender’s first proposal is your only option or that every foreclosure case follows the same path.
Questions to ask before choosing Chapter 13
The decision should be based on numbers, not just hope. Start by looking at your current income, regular mortgage payment, property taxes and insurance, household expenses, and total amount past due. Then consider whether the hardship was temporary or likely to continue.
A few questions are especially useful:
- Can you resume the regular mortgage payment immediately or very soon?
- Can your income support both the mortgage and a Chapter 13 plan payment for several years?
- Are credit cards, medical bills, tax debt, or car payments making it harder to save the home?
- Is there meaningful equity in the property that you want to protect?
- Has the lender already filed a foreclosure lawsuit or scheduled a sale?
The answers may point toward Chapter 13, another foreclosure-defense strategy, a negotiated resolution, or a planned move that helps your family regain stability. There is no one-size-fits-all answer, and a plan that works for one homeowner may not work for another.
Timing matters in Illinois foreclosure cases
It is usually easier to evaluate options before a foreclosure sale is scheduled. Early action may provide more room to request mortgage documents, explore loss-mitigation options, correct servicing errors, or prepare a Chapter 13 filing carefully.
That said, help may still be available later in the process. A pending foreclosure case, judgment, or sale date does not automatically mean there is nothing left to do. The precise procedural stage matters, and Illinois deadlines can be strict. Bringing all court papers, lender letters, payment records, and any loan-modification communications to a consultation can help a lawyer give a clearer assessment.
Avoid signing agreements you do not understand simply because a deadline is approaching. Some repayment plans, forbearance offers, and modification proposals may be helpful. Others may postpone the problem without making the payment affordable. Review the full terms, including any lump-sum payment, trial payment, interest change, escrow adjustment, or waiver of rights.
Chapter 13 is a commitment, not a quick fix
A successful Chapter 13 case requires steady follow-through. You must make plan payments, stay current on ongoing mortgage obligations, provide financial information, and notify your attorney if your income or expenses change. Missing payments can put the case and the home at risk.
Still, for homeowners who experienced a temporary setback and now have dependable income, the structure can provide breathing room. It replaces the uncertainty of collection calls and foreclosure deadlines with a court-supervised plan for moving forward.
At Michelotti & Associates Ltd., homeowners facing debt pressure can discuss their circumstances in a confidential consultation, including video appointment options when travel is difficult. A clear review of your budget and foreclosure status can help you make a decision based on facts rather than fear.
Your home is more than a financial asset. It is where your family lives, plans, and recovers from hard seasons. If foreclosure is approaching, seek advice early enough to understand your choices and choose the path that supports a more secure future.
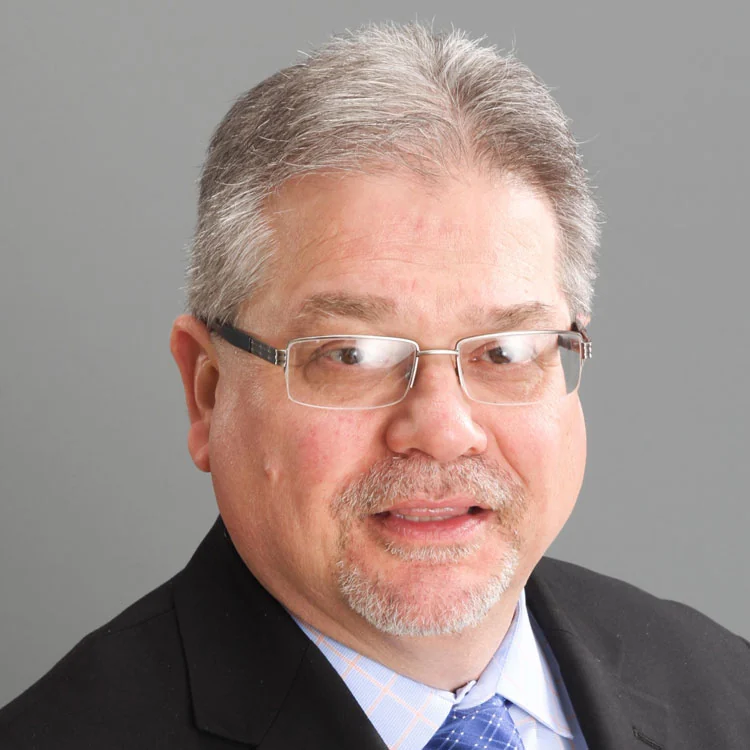
Written and reviewed by Joseph C. Michelotti
Attorney at Law · practising in Illinois since 1983 · McGill University, 1979 · member, American Immigration Lawyers Association (AILA)
This article is general information, not legal advice about your situation. Reading it does not create an attorney–client relationship.
Here for you when you need us most.
Free consultation. Payment plans available. All major credit cards accepted.