
Home/Insights/Insights
Debt Collection Guide for Illinois Consumers
This debt collection guide explains what Illinois consumers can do when collectors call, send letters, or file suit, and when legal help may protect you.
Insights · 4 November 2026
A debt collector’s call can make an ordinary workday feel uncertain. A letter in the mail may raise even bigger questions: Is this debt really mine? Can they take my paycheck? What happens if I do not respond? This debt collection guide is designed for Illinois consumers who need clear next steps, not more pressure.
Debt problems are personal, but you do not have to handle them alone or make decisions in a panic. Whether the debt involves a credit card, medical bill, personal loan, old utility account, or a lawsuit, the right response depends on the details and the deadline.
Start by identifying what you received
Not every collection notice means the same thing. A phone call, collection letter, demand from a law firm, notice of wage garnishment, and court summons each call for a different response. Before paying, promising payment, or ignoring the communication, save it.
Write down the collector’s name, the original creditor, the account number shown, the amount claimed, and the date you received the notice. Keep envelopes, emails, voicemails, and screenshots of text messages. These records can help you confirm whether the account is accurate and whether the collector is following the law.
A debt may have been sold more than once. That does not automatically make it invalid, but it can create errors. The name of the company contacting you may be unfamiliar even when the original debt was legitimate. Ask who currently owns the account and who the original creditor was.
Do not mistake a collection letter for a court case
A collection letter is a demand for payment. A lawsuit is a legal action filed in court. The difference matters.
If you receive a summons and complaint, or other court papers, do not set them aside because you are unsure what to do. Failing to respond by the deadline can allow the creditor or debt buyer to request a default judgment. Once a judgment is entered, the creditor may have additional collection options, including possible wage garnishment or bank account action, subject to Illinois law and exemptions.
Court papers often contain a case number, the name of a court, a plaintiff, and a response deadline. Check those details promptly. Even if you believe the debt is valid, responding may give you time to explore defenses, negotiate, or evaluate broader debt-relief options.
Confirm the debt before you pay
A collector should provide information that allows you to identify the debt. Review the balance carefully. Look for an explanation of interest, fees, payments already made, and the name of the original creditor.
If you do not recognize the debt, believe the amount is wrong, or think the account resulted from identity theft, act quickly. You may have the right to dispute the debt and request verification. A written dispute creates a record of your position and is usually more useful than a verbal conversation. Keep a copy of what you send and proof that it was delivered.
Be thoughtful before making a small “good faith” payment on an old account. Depending on the facts and applicable law, a payment or written acknowledgment can affect how a creditor approaches the account. It may also complicate questions about the time limit for filing suit. The age of a debt matters, but an old debt is not necessarily unenforceable, and collectors may still seek voluntary payment. A lawyer can review the specific account history before you make a decision.
Know the limits on collection conduct
Debt collectors are not free to use any tactic they choose. Federal and state laws can limit harassment, false statements, improper disclosures, and certain contact practices. For example, a collector generally cannot threaten action it does not intend or have the legal right to take, falsely claim to be connected to the government, or repeatedly contact you to harass you.
Collectors also generally cannot discuss your debt with other people, except in limited circumstances. They may be able to seek location information, but they should not reveal the debt to your family, coworkers, or employer. If calls are coming to your workplace, tell the collector if your employer does not permit those calls.
You can ask a collector to communicate in writing or tell it to stop contacting you. That request can reduce stressful calls, but it does not erase a valid debt or stop a lawsuit. In some situations, written communication can be the better choice because it gives you a clearer paper trail.
If you believe a collector has crossed the line, preserve the evidence. Note the date, time, phone number, caller’s name, and what was said. Save letters and messages. A lawyer can help you determine whether the conduct violates consumer protection law and how that affects your options.
If you are sued, respond before the deadline
A debt lawsuit does not mean you have no defense. The party suing must generally show it has the right to bring the claim and support the amount it seeks. Documentation can be especially important when the plaintiff is a debt buyer rather than the original creditor.
Do not assume the court will sort this out without your participation. If you do not appear or respond, the other side may obtain a judgment without having to fully litigate disputed facts. Read every page of the paperwork, calendar the deadline, and consider speaking with an Illinois consumer debt attorney as soon as possible.
There may be defenses based on mistaken identity, payment, an incorrect balance, lack of sufficient documentation, the age of the claim, or improper service. Whether any defense applies depends on the facts. A realistic legal review is valuable even when the debt appears difficult to challenge, because it can clarify the risks and reveal options for resolution.
Understand wage garnishment and bank account concerns
Many people fear that a collector can immediately take their wages or empty their bank account. In most cases, a creditor needs to follow a legal process first. For ordinary consumer debts, that commonly means obtaining a court judgment before pursuing garnishment or other collection remedies.
Illinois law provides protections and exemptions, and certain income may receive special treatment. The amount that can be withheld from wages is limited by law. Social Security benefits, veterans’ benefits, unemployment benefits, and other protected funds may also have protections, though how those protections apply can depend on where the funds are held and the type of debt involved.
Tax debts, child support, federal student loans, and other obligations can involve different collection rules. That is one reason generic internet advice can be risky. The type of debt and the stage of collection both matter.
Consider the solution that fits your whole financial picture
A payment arrangement can make sense when the debt is manageable, the balance is accurate, and the agreement leaves room for necessities such as housing, food, transportation, and medical care. Get settlement or payment terms in writing before sending money. Make sure the agreement states what happens after the final payment and whether the account will be considered resolved.
But a single collector may be only one part of a larger problem. If several credit cards, medical bills, personal loans, collection accounts, tax obligations, or foreclosure concerns are competing for your income, a one-account settlement may not create lasting relief.
In that situation, it may be worth discussing broader options. Chapter 7 bankruptcy can help eligible people discharge certain unsecured debts. Chapter 13 bankruptcy may allow someone with regular income to repay debts through a structured plan while addressing issues such as mortgage arrears. Filing bankruptcy can also trigger an automatic stay that generally stops many collection actions, lawsuits, garnishments, and creditor calls while the case is pending. The right option depends on income, assets, goals, household needs, and the debts involved.
A practical debt collection guide: what to do this week
Take action in a calm, organized order. First, gather every letter, bill, court document, and recent credit report entry connected to the account. Next, verify who is contacting you and compare the claimed balance to your records. If you received court papers, treat the response deadline as urgent.
Then look at your full budget, not just the payment the collector is demanding. Paying a collector should not force you to miss rent, utilities, groceries, insurance, or essential transportation. Finally, seek legal advice before signing a settlement agreement, accepting a repayment plan you cannot sustain, or ignoring a lawsuit.
Financial pressure often makes people feel they must choose immediately between paying everything and doing nothing. There are usually more options than that. Clear information, timely action, and dependable legal guidance can help you protect your rights and move toward a more secure future.
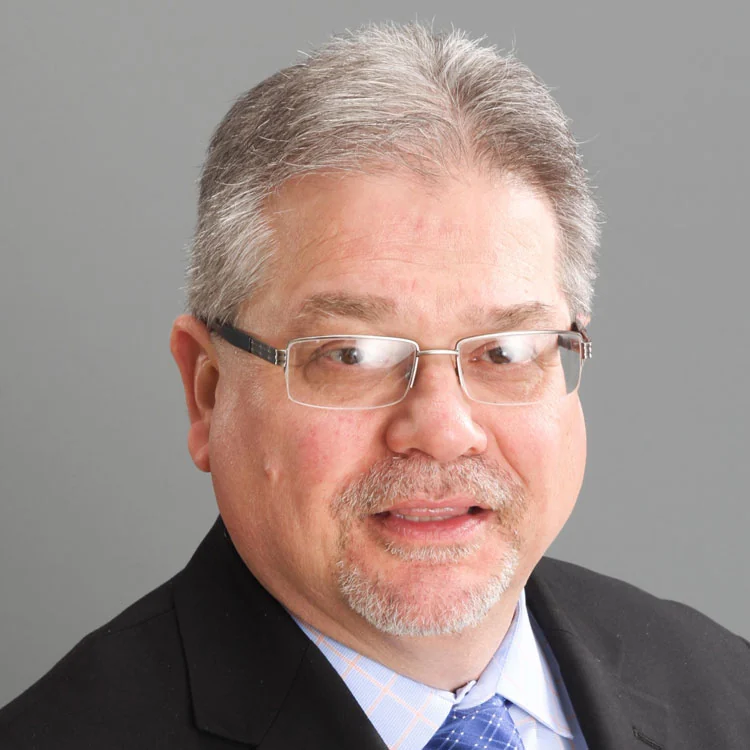
Written and reviewed by Joseph C. Michelotti
Attorney at Law · practicing in Illinois since 1983 · McGill University, 1979 · member, American Immigration Lawyers Association (AILA)
This article is general information, not legal advice about your situation. Reading it does not create an attorney–client relationship.
Here for you when you need us most.
Free consultation. Payment plans available. All major credit cards accepted.