
Home/Insights/Insights
Bankruptcy Versus Wage Garnishment in Illinois
Compare bankruptcy versus wage garnishment in Illinois. Learn when an automatic stay may stop deductions and what debt relief may mean for your pay today.
Insights · 27 October 2026
When money is already tight, seeing part of your paycheck taken before it reaches your bank account can make every bill feel impossible. The choice between bankruptcy versus wage garnishment is not simply about stopping a deduction. It is about understanding why the garnishment started, what legal protections may apply, and which path can help you regain financial stability.
For many Illinois families, wage garnishment is the final stage of a debt problem that has been building for months or years. A credit-card balance, medical bill, personal loan, or old account may lead to a lawsuit, a judgment, and then a court order requiring an employer to withhold wages. You still have options, even if the garnishment has already begun.
What Wage Garnishment Can Mean for Your Household
A wage garnishment, often called a wage deduction in Illinois, generally allows a creditor to collect from your pay after obtaining a court judgment. Your employer receives notice and is legally required to withhold the required amount. That can feel embarrassing, but your employer is not the party pursuing the debt. The order comes from the legal process.
For many ordinary consumer debts in Illinois, the amount that may be withheld is limited by state and federal law. Illinois law is often more protective than the federal limit for standard creditor garnishments. Still, the loss of even a modest percentage of each paycheck can disrupt rent, groceries, transportation, child care, and other necessities.
Not every garnishment follows the same rules. Child support, certain tax debts, federal student loans, and other government-related obligations can involve different collection powers and different withholding limits. Some may not require a creditor to first obtain the same type of court judgment required for a typical credit-card lawsuit.
That difference matters. Before choosing a response, you need to know who is collecting, whether there is a judgment, how much is being withheld, and whether the debt is one bankruptcy can discharge or address.
Bankruptcy Versus Wage Garnishment: The Key Difference
Wage garnishment is a collection tool. Bankruptcy is a legal process that may stop collection activity and provide a structured way to deal with qualifying debt.
If a creditor is taking money from your wages for a dischargeable debt, filing bankruptcy may trigger an automatic stay. The automatic stay is a court-ordered protection that generally requires creditors to stop most collection actions right away, including many wage garnishments, lawsuits, collection calls, and bank levies.
The stay is powerful, but it is not a one-size-fits-all solution. It does not usually stop current child support obligations, and it may not fully stop certain tax collection or criminal-related obligations. It also does not erase every type of debt. A careful review of your specific debts, income, assets, and goals is essential before filing.
How the Automatic Stay Can Help
For someone facing a credit-card garnishment, the immediate benefit of a bankruptcy filing may be relief from the ongoing paycheck deduction. Once the case is filed, creditors and their attorneys are generally notified, and the garnishment should stop if it is covered by the stay.
Timing is important. A creditor may have already collected money before the filing date, and whether any previously garnished wages can be recovered depends on the facts, the amount taken, the timing, and applicable bankruptcy rules. It is best to get legal advice quickly rather than assume prior deductions will automatically be returned.
The automatic stay also gives you breathing room. Instead of responding to a new collection demand every week, you can assess your financial situation under the protection of the bankruptcy court.
When Chapter 7 May Be the Better Fit
Chapter 7 bankruptcy is often considered when a person has primarily unsecured debts, such as credit cards, medical bills, payday loans, and personal loans, and lacks the income to realistically repay them. If eligible, Chapter 7 can eliminate many qualifying unsecured debts in a relatively short period.
For a qualifying consumer debt garnishment, a Chapter 7 filing may stop the wage deduction and, after discharge, remove the creditor's legal right to continue collecting that discharged balance. This can be a meaningful reset for a household that has fallen behind because debt payments and garnishments consume too much of its income.
Chapter 7 is not right for everyone. Eligibility is based in part on income and household circumstances. You must also consider property, vehicle equity, homeownership, recent financial transfers, and whether you have debts that are not dischargeable. A person who wants to catch up on a mortgage or car loan may need a different approach.
When Chapter 13 May Offer More Control
Chapter 13 bankruptcy creates a court-supervised repayment plan, usually lasting three to five years. It can be especially useful for individuals with regular income who need time to address more than one serious financial problem.
For example, someone may be dealing with a wage garnishment while also behind on a mortgage, car payment, taxes, or other priority debts. Chapter 13 may stop many collection actions and allow the person to make a single plan payment designed around their income and required expenses.
This does not mean every debt disappears. The plan may require repayment of certain obligations, and monthly payments must be realistic and sustainable. But Chapter 13 can replace the uncertainty of separate creditors pursuing separate collection actions with a more organized path forward.
When Bankruptcy May Not Be Necessary
Bankruptcy is a serious legal tool, not the only answer to wage garnishment. In some situations, it may be possible to challenge the underlying judgment, raise an exemption, negotiate a settlement, or address a procedural issue in the collection case.
A garnishment based on mistaken identity, an improper lawsuit notice, an already-paid debt, or the wrong balance may require a different legal response. Likewise, if you have only one manageable debt and enough income to settle it, bankruptcy may be more relief than you need.
The problem is that waiting can narrow your options. Once a judgment is entered, a creditor may have stronger collection leverage. If you have been served with a lawsuit, received notice of a wage deduction, or noticed a smaller paycheck, do not set the paperwork aside. The dates and documents can matter.
Questions to Ask Before You Decide
A useful starting point is to look beyond the current garnishment. Ask whether this creditor is the only one pursuing you, whether you are behind on secured debts such as a mortgage or vehicle loan, and whether the lost wages are causing you to miss necessities.
You should also consider the type of debt. Credit-card and medical debt are treated differently from student loans, recent taxes, child support, and debts connected to fraud or certain court judgments. Your income, household size, assets, and recent financial history can also affect whether Chapter 7 or Chapter 13 is available and appropriate.
Do not assume that having a job prevents you from filing bankruptcy. Many people who seek debt relief are working hard and still cannot keep up with interest, late fees, lawsuits, and deductions from their pay. Bankruptcy laws exist in part to give honest people a lawful chance to stabilize their finances.
Take Action Before the Next Paycheck
Gather the documents you have received, including the lawsuit papers, judgment, wage deduction notice, recent pay stubs, and a list of all debts. Knowing the name of the creditor and the court case number can help an attorney evaluate what is happening quickly.
Avoid making decisions based solely on a collection caller's urgency. A settlement may sometimes make sense, but it should be reviewed carefully. You deserve to know whether the proposed payment will actually resolve the debt, whether the garnishment will end, and whether another creditor may be waiting in line.
Michelotti & Associates Ltd. helps Illinois residents understand their debt-relief options with clear, practical guidance. A conversation about your wages, debts, and goals can help you decide whether challenging the garnishment, pursuing bankruptcy, or taking another step offers the strongest path toward security.
You do not have to let a wage deduction define your future. The sooner you understand your options, the sooner you can make a plan that protects your paycheck, your household, and your peace of mind.
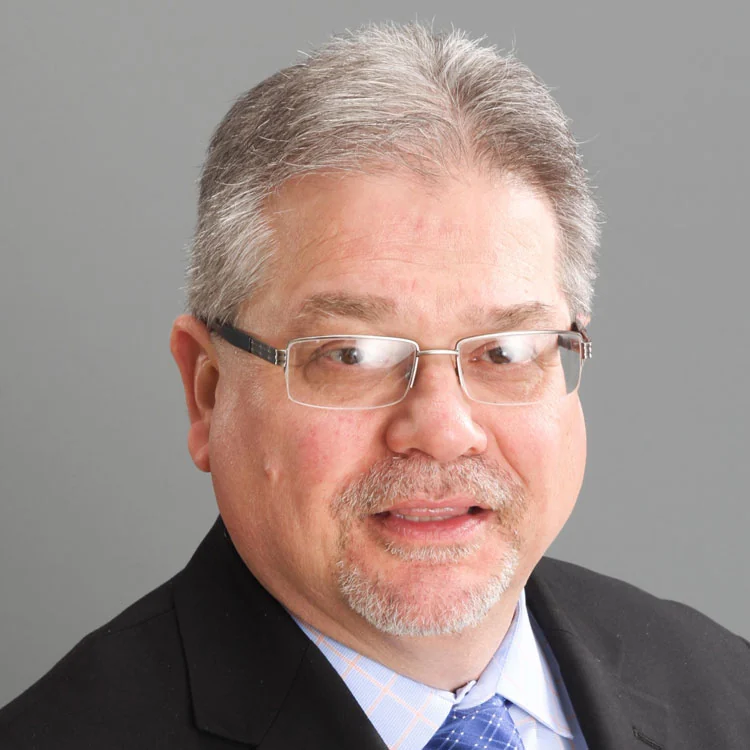
Written and reviewed by Joseph C. Michelotti
Attorney at Law · practising in Illinois since 1983 · McGill University, 1979 · member, American Immigration Lawyers Association (AILA)
This article is general information, not legal advice about your situation. Reading it does not create an attorney–client relationship.
Here for you when you need us most.
Free consultation. Payment plans available. All major credit cards accepted.