
Home/Insights/Insights
Foreclosure Mediation Guide for Illinois Homeowners
A foreclosure mediation guide for Illinois homeowners explains what to bring, how talks work, and when bankruptcy or other options may help save a home.
Insights · 11 October 2026
The date on a foreclosure notice can make it feel as if you have already lost your home. You have not. This foreclosure mediation guide explains how mediation may give Illinois homeowners time, information, and a structured opportunity to discuss a realistic solution with their mortgage lender before the case moves further.
Mediation is not a promise that a lender will reduce your payment or stop foreclosure permanently. It is, however, a chance to have a focused conversation about available options, with a neutral third party helping keep the process productive. For many families, that conversation is easier to manage than trying to get clear answers through repeated calls to a loan servicer.
What foreclosure mediation is designed to do
Foreclosure mediation is a meeting between the homeowner and the lender or loan servicer, usually with a trained neutral mediator. The mediator does not act as your lawyer, does not decide who is right, and cannot force either side to accept an agreement. Their role is to help both parties exchange information, identify possible resolutions, and negotiate in good faith.
In Illinois, foreclosure cases generally move through the court system. Some counties and courts offer mediation or loss-mitigation programs, while procedures and eligibility can differ by location. A referral may come through the court, a housing counseling agency, or another local program. If mediation is available, acting promptly matters. Missing court dates, deadlines, or document requests can narrow your choices.
The purpose is usually practical: Can the homeowner afford a modified payment? Is a repayment plan workable? Is there a temporary hardship that could support forbearance? If keeping the home is not realistic, can the parties reach an orderly solution that reduces the financial and personal damage?
What can happen in foreclosure mediation?
Every case is different, but mediation often centers on the lender's loss-mitigation options. A loan modification may change the interest rate, extend the loan term, add past-due amounts to the balance, or otherwise adjust the payment. A repayment plan may spread delinquent payments over several months. Forbearance may pause or reduce payments for a defined period, often when a borrower expects a short-term hardship to improve.
Other outcomes may include reinstatement, where the borrower pays enough to bring the loan current, or a payoff if the property can be sold or refinanced. If retaining the home is not possible, a short sale or deed in lieu of foreclosure may be discussed. These options involve serious trade-offs, including credit consequences, tax questions, remaining debt, and the need to move. They should not be accepted without understanding the terms.
Sometimes mediation does not produce an agreement. That does not automatically mean the homeowner has no defenses or no remaining options. It means the case needs a careful review of the foreclosure timeline, the mortgage documents, the servicer's actions, the homeowner's finances, and any other available legal relief.
How to prepare for a foreclosure mediation session
Preparation gives you a better chance of receiving a meaningful review rather than another request for documents. The lender will usually evaluate both your hardship and your current ability to pay. Be candid. An unrealistic budget may lead to an agreement that fails a few months later.
Bring the documents requested in your mediation notice or loan-servicer packet. In most cases, that includes recent pay stubs or proof of income, recent bank statements, federal tax returns, a completed financial statement, a list of monthly household expenses, and a hardship letter. If your income comes from self-employment, benefits, rental income, or support payments, gather records that clearly show those amounts.
Your hardship letter should be honest and specific. Explain what changed: a job loss, reduction in hours, illness, divorce, unexpected family expenses, or another event. Then explain whether the hardship is temporary or ongoing. The goal is not to tell the most dramatic story. It is to give the lender enough accurate information to evaluate a solution.
Keep copies of everything you submit. Write down the date, the person or department that received it, and any confirmation number. Mortgage servicing records can be confusing, especially when a loan has changed hands or a borrower has submitted documents more than once. Organized records can prevent avoidable delays.
Know your real monthly budget
Before the meeting, calculate what your household can truly pay for housing. Include the proposed mortgage payment along with property taxes, insurance, utilities, food, transportation, child care, medical needs, and other required expenses. Do not agree to a payment based on overtime that is not reliable or financial help that may disappear.
If you have credit card balances, medical bills, tax debt, car payments, or collection lawsuits, those pressures belong in the larger conversation about affordability. A mortgage modification can be helpful, but it may not resolve a household's broader debt crisis.
Ask clear questions before signing anything
If an offer is made, ask how the payment was calculated and whether it will change later. Ask whether unpaid interest, fees, and missed payments are being added to the loan balance. Ask whether there is a trial period, what must be paid during that period, and what happens if a payment is late.
If the proposal involves a short sale, deed in lieu, or another option that ends homeownership, ask whether the lender will waive any remaining balance. Get important terms in writing. Do not assume that turning over the property ends every possible obligation.
When mediation may not be enough
Mediation can be valuable, but it is only one tool. It may not solve the problem if the proposed payment remains unaffordable, the lender will not approve a modification, or a foreclosure sale is approaching. It also may not address other debts that are consuming the income needed to maintain the home.
For some Illinois homeowners, Chapter 13 bankruptcy can provide time and structure. Filing bankruptcy usually triggers an automatic stay, which can pause most collection activity and foreclosure proceedings while the case is pending. A Chapter 13 plan may allow a homeowner to catch up on mortgage arrears over time while continuing to make current mortgage payments. Whether that approach is realistic depends on stable income, the amount owed, household expenses, and the overall debt picture.
Chapter 7 bankruptcy may help eliminate certain unsecured debts, such as qualifying credit card or medical debt, but it does not create a long-term plan to cure missed mortgage payments. In some circumstances, reducing unsecured debt can improve a household's ability to focus on the mortgage. In others, Chapter 13 or a non-bankruptcy resolution may make more sense.
The timing matters. Waiting until the week of a scheduled sale can leave fewer options and more pressure. A lawyer can review the foreclosure case, explain deadlines, evaluate defenses, and help you decide whether mediation, a workout application, bankruptcy, or another path best supports your family's stability.
Common mistakes that can hurt a foreclosure case
The first mistake is ignoring mail because it is overwhelming. Court papers, mediation notices, and servicer requests may contain deadlines that affect your rights. Open them, save them, and get help understanding them.
The second is relying on verbal assurances. If a representative says a sale will be postponed or documents are complete, request written confirmation when possible. Continue checking your case status and meeting all deadlines unless you have clear written instructions otherwise.
The third is paying a company that promises to stop foreclosure for an upfront fee. Be cautious with anyone who guarantees a loan modification, tells you to stop speaking with your lender, or asks you to sign documents you do not understand. Homeowners facing a crisis deserve straight answers, not another financial risk.
A foreclosure mediation guide starts with timely action
A foreclosure case is stressful because it affects more than a house. It affects routines, children, savings, and the sense of security a home can provide. Mediation can create room to talk through the numbers and seek a workable resolution, but it works best when you arrive prepared and act before deadlines close in.
If you are facing foreclosure in Illinois, a prompt legal review can help you understand the choices in front of you and avoid making decisions out of fear. Michelotti & Associates Ltd. can help homeowners assess their foreclosure and debt-relief options with clear, practical guidance. The next useful step is often simply getting the facts, organizing the documents, and making a plan that protects your future as much as possible.
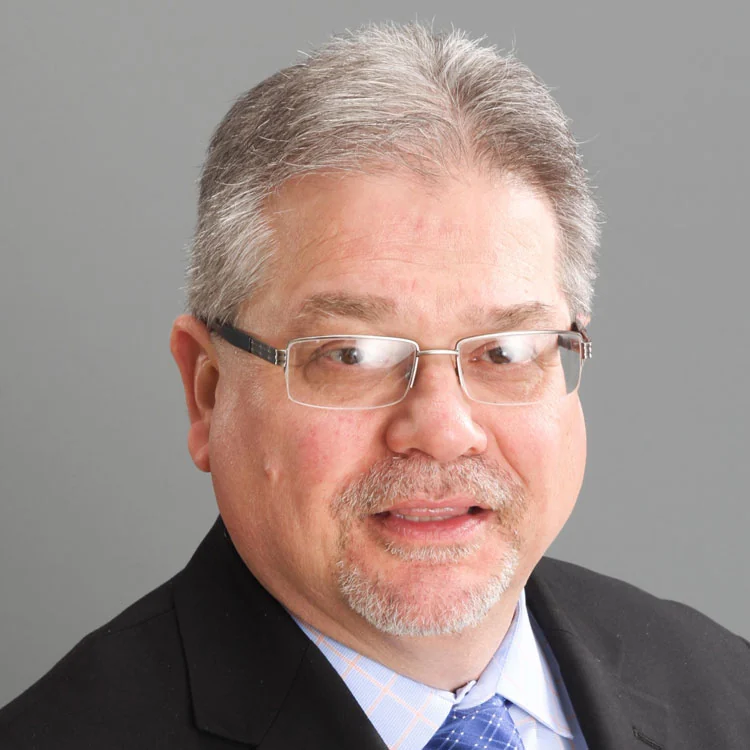
Written and reviewed by Joseph C. Michelotti
Attorney at Law · practising in Illinois since 1983 · McGill University, 1979 · member, American Immigration Lawyers Association (AILA)
This article is general information, not legal advice about your situation. Reading it does not create an attorney–client relationship.
Here for you when you need us most.
Free consultation. Payment plans available. All major credit cards accepted.